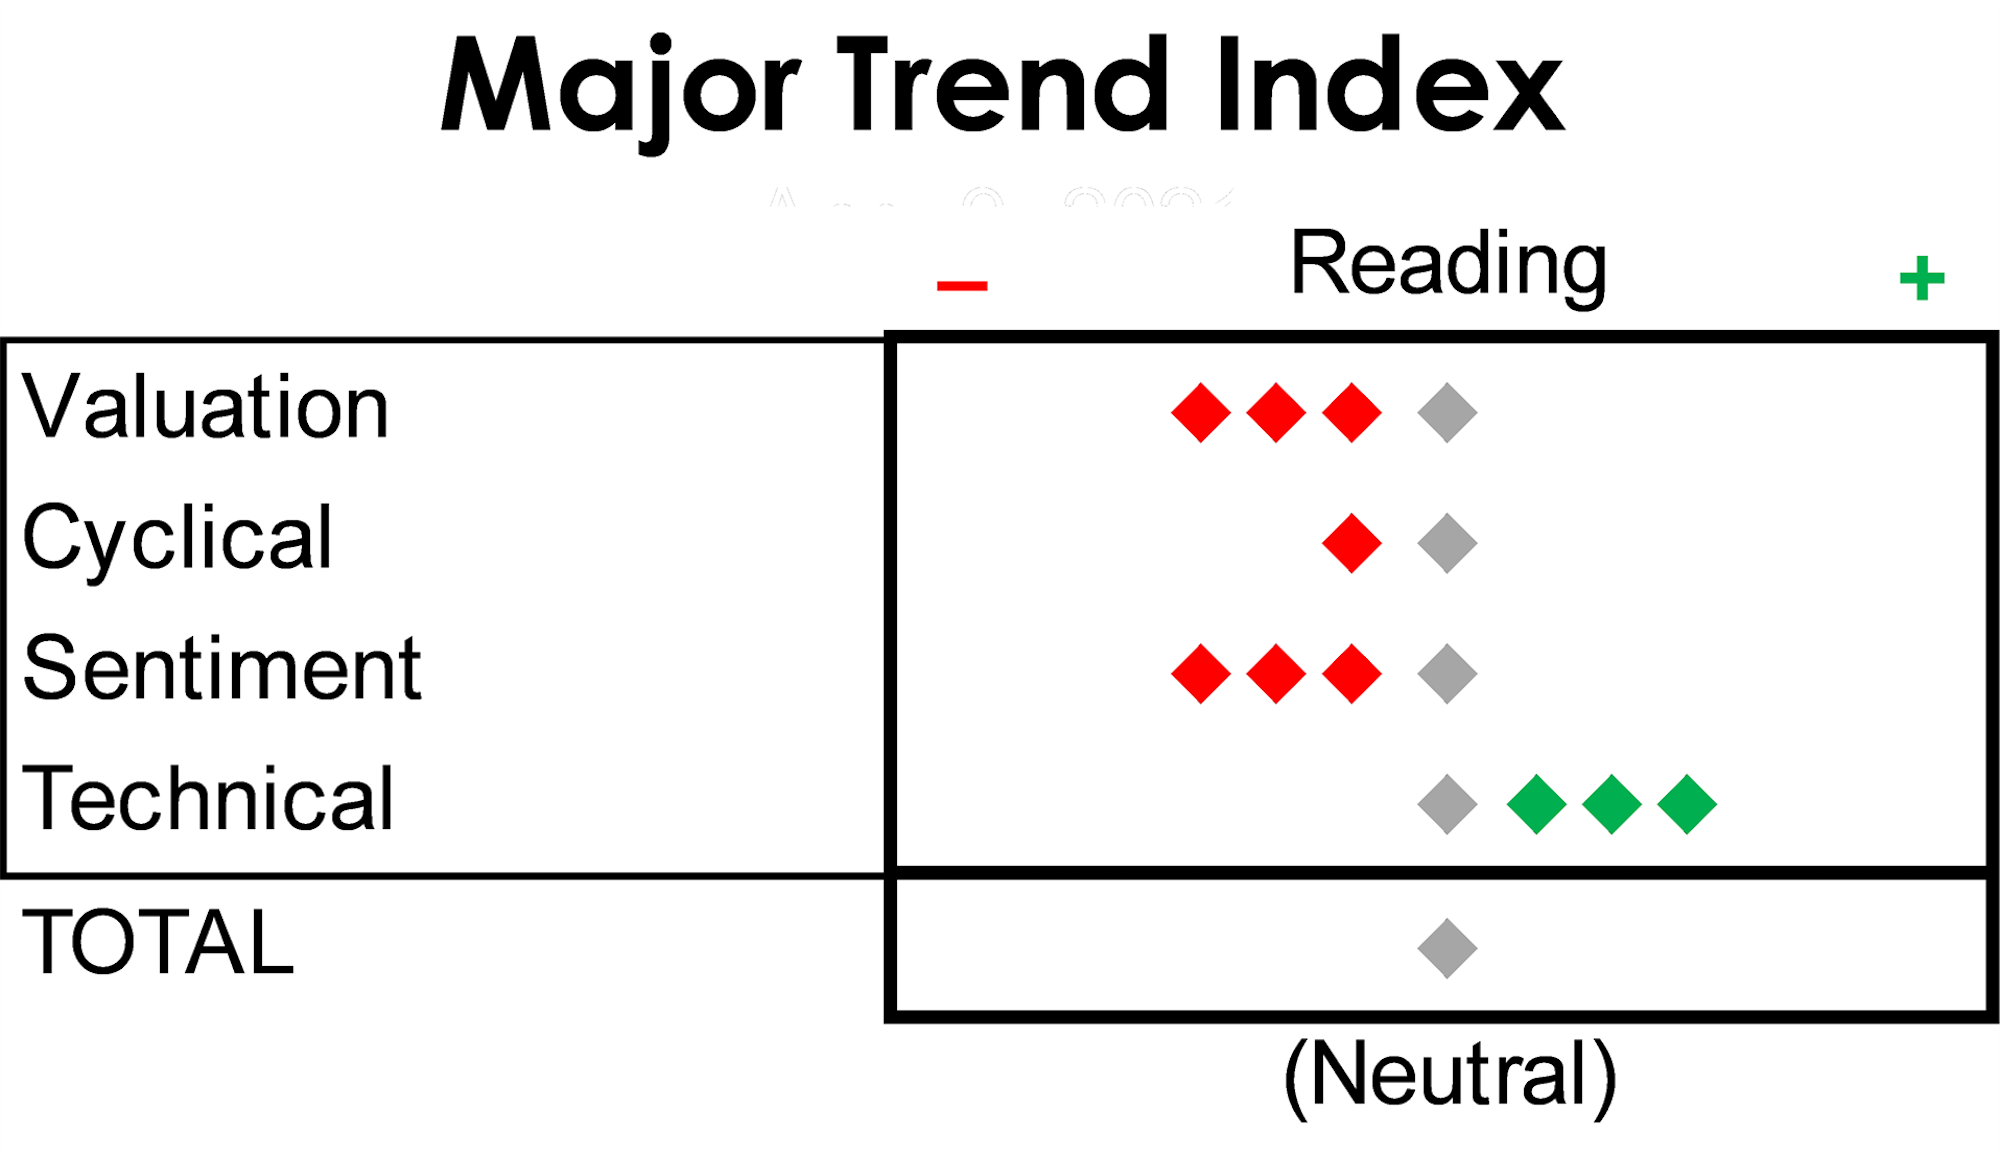
The final full week of August largely mirrored the month’s overall performance themes. Large-cap tech, specifically software firms, carried both the Nasdaq Composite (+90 bps) and the S&P 500 (+50 bps). The monthly gain for the former stands at 4% with the latter at 3%. Small and mid-caps posted 1%-1.5% losses for the week, flattening their month-over-month returns.
That uneven return profile knocked a few breadth indicators down a peg or two during August. On the whole, that subset still scores a little better than neutral but, like Michigan or Pennsylvania, is currently the biggest “swing state” for the Technical category and the standing of the MTI itself. The Major Trend composite score remains at Neutral and net equity exposure in Leuthold tactical accounts is a moderate 56%.
In lovely Jackson Hole, Wyoming, Fed Chair Warsh leaned hawkish on inflation readings, reiterating the commitment to a 2% PCE goal. This added credibility to the notion of an independent central bank, and some yield to the front end of the curve. The two-year Treasury ended the week at 4.35—the highest since January. Fed fund futures have also adjusted, now seeing two hikes as the most likely path over the next four Fed meetings. We anticipate a more hawkish Fed would deliver some relief to the glaringly negative inflation subcategory of our Cyclical work. Of course, monetary tightening would also adversely affect the mostly neutral liquidity factors, but the tradeoff seems necessary at this point.
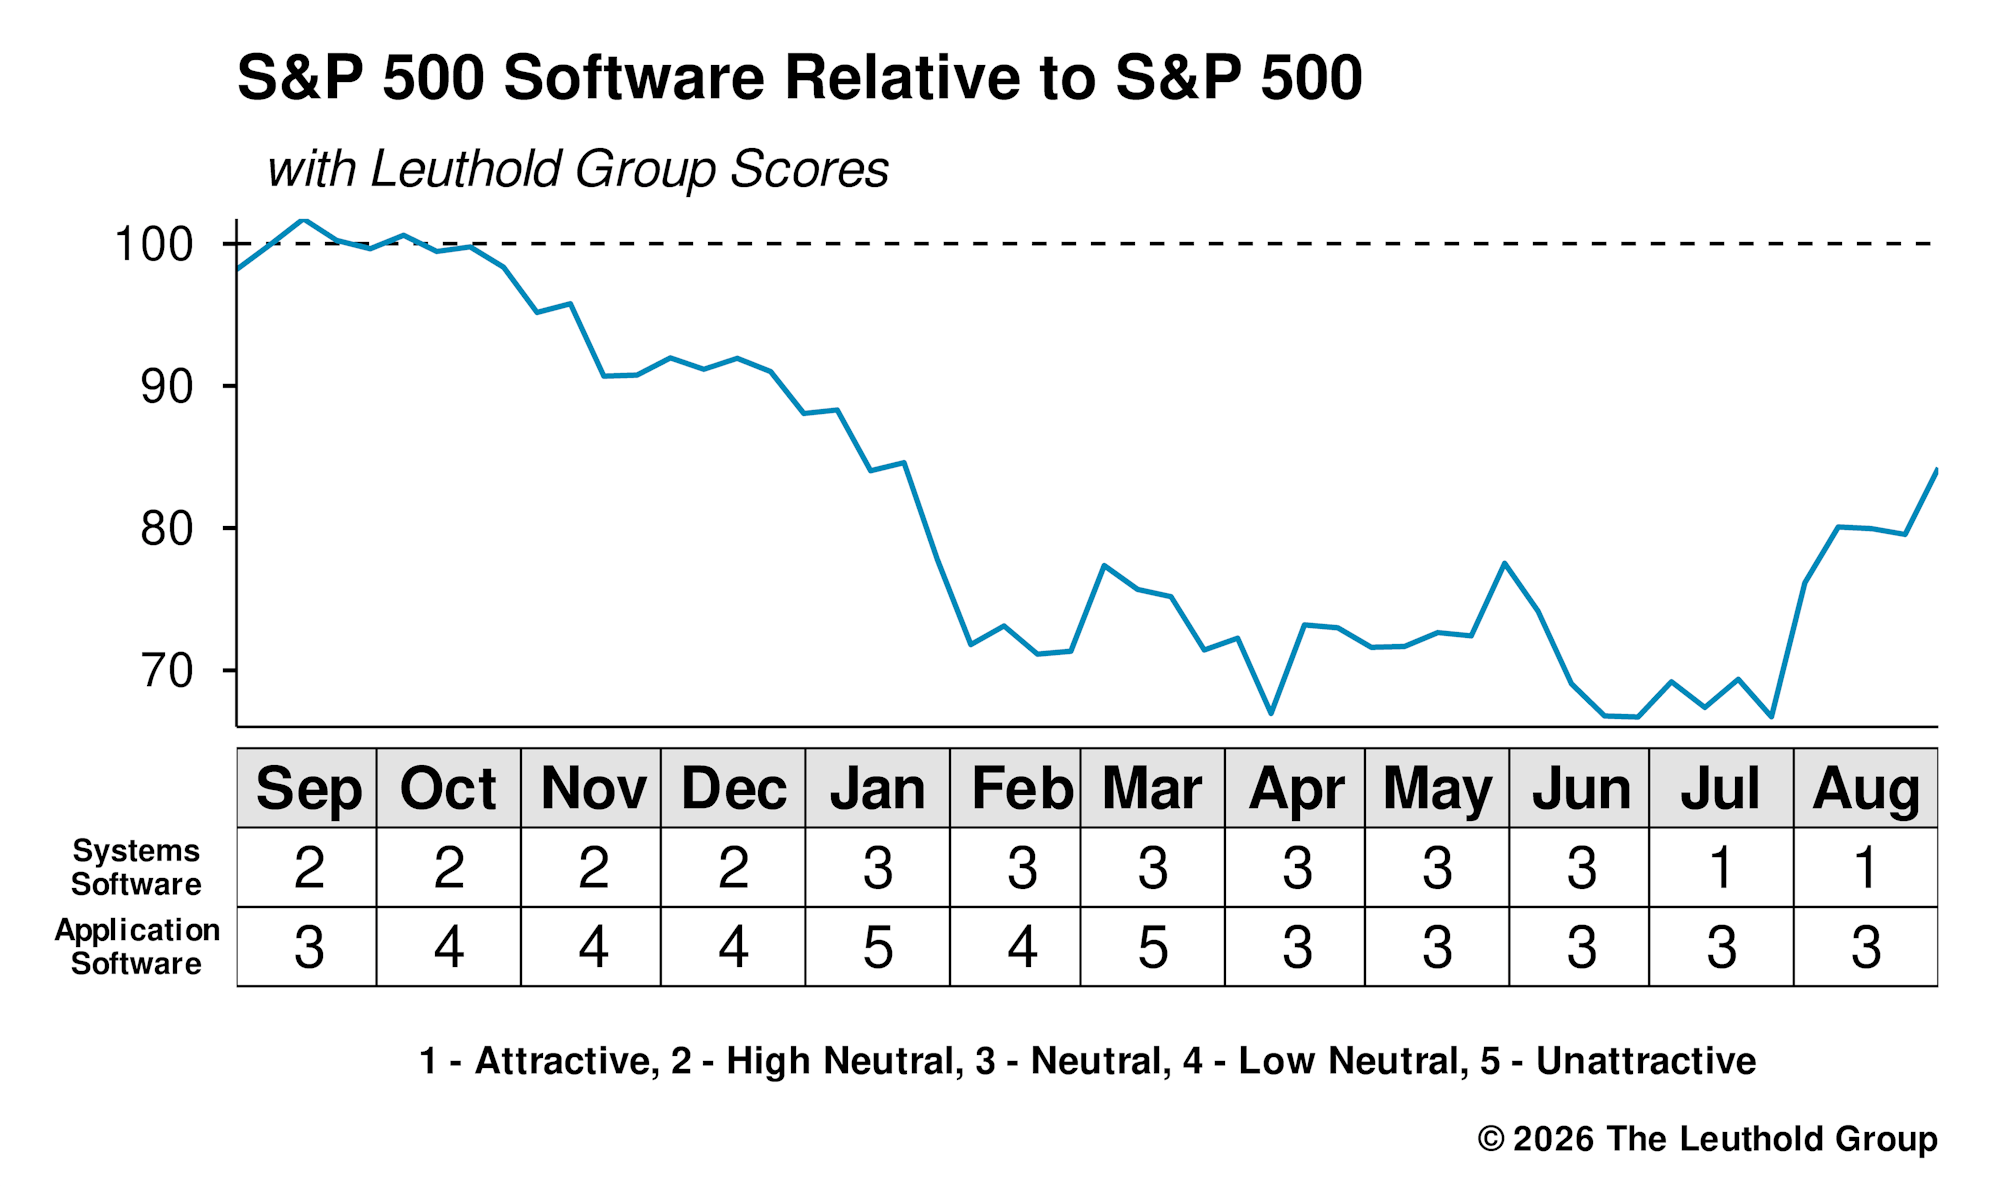
As mentioned, software stocks, which cratered on AI concerns last spring, have been carrying the market for the past five weeks. The S&P 500 Software Index gained 32% over that period versus a 4% advance in the Cap Weighted S&P 500. Our Group Selection (GS) Scores, which drive our long equity sleeve, sniffed out this potential earlier in the summer: GS Score downgrades across multiple AI-beneficiary industries coincided with upgrades in groups previously viewed as vulnerable to AI disruption.
In our mid-July rotation, we added Systems Software equities to the Leuthold Select Industries portfolio as valuation and fundamental scores looked very favorable. Technical action for that software group also suggested a near-term bottom. Dampening the volatility of the AI trade within our portfolio was a considerable bonus.
In the future, this seesaw preference for exposure on either side of the AI fence may come to an end. Perhaps those who have been at odds can coexist better than feared. For now, it’s the key question in portfolio construction. We’ll rely on our GS Scores to point the way.
The Major Trend Index is designed to recognize major market trends rather than intermediate moves, combining around 130 individual components to assess the overall health of the stock market. Revisions and weight adjustments are made from time to time.
 Subscribe to Advisor Newsletter